
Updated on November 6, 2026
Your savings may grow in dollar terms even while they lose purchasing power. Inflation can explain part of that erosion, but government policies may also influence how much savers earn on their money.
Understanding these policies can reveal hidden costs and may help you evaluate ways to preserve your wealth.
One such policy has a name few people recognize, despite its potentially far-reaching consequences: financial repression.
Please note: All content is provided strictly for general informational and educational use. This information should not be interpreted as financial advice, nor should it replace professional consultation with an advisor.
What does financial repression mean?
Financial repression refers to government policies that influence financial markets to direct capital toward preferred borrowers, often at below-market interest rates.
“Financial repression may be part of the toolkit deployed to cope with the most recent surge in public debt in advanced economies.”[1]
How does financial repression work?
Financial repression works by:
- Restricting competition among financial institutions.
- Limiting investment choices.
- Creating incentives or requirements to purchase government debt.
These measures can increase demand for government securities and reduce the interest rates that governments must offer to attract investors. In competitive markets, those rates would reflect the supply of available capital and demand from borrowers.
When borrowing costs remain below inflation, governments can repay their obligations with currency that has lost purchasing power.
This relationship between real and nominal interest rates helps explain how financial repression can reduce the real value of government debt over time.
What are some examples of financial repression?
- Interest rate ceilings: Beginning in 1933, the United States imposed Regulation Q, which capped the interest rates banks could pay on savings and time deposits[2].
- Capital controls: In 1998, Malaysia restricted transfers of capital abroad and temporarily prevented foreign investors from repatriating proceeds from securities sales[3].
- Mandatory government debt holdings: Under India’s Statutory Liquidity Ratio, banks were required to hold a prescribed share of their liabilities in liquid assets, including government securities. The ratio reached 38.5% in 1990[4].
- Directed credit: Beginning in the late 1960s, India introduced policies directing banks to prioritize financing for agriculture, exports, and small businesses[5].
- Restrictions on financial competition: Before the 1994 Riegle-Neal Act, U.S. banking laws restricted banks from opening branches across state lines[6].
Why do governments use financial repression?
Governments use financial repression to help manage debt without imposing the full costs of higher taxes or spending reductions.
They have several options for managing excessive debt, but each approach presents economic and political challenges.
Financial repression offers another mechanism: reduce the cost of servicing debt while inflation diminishes the real value of existing obligations.
If a government borrows $10,000 at 2% annual interest while inflation averages 5%, it pays $200 in annual interest. Meanwhile, inflation reduces the purchasing power of its debt by approximately $476 over the same period.
Reinhart and Sbrancia estimated that financial repression generated annual interest expense savings equivalent to approximately 1%–5% of GDP across the 12 countries they studied between 1945 and 1980[1].
What are the costs of financial repression?
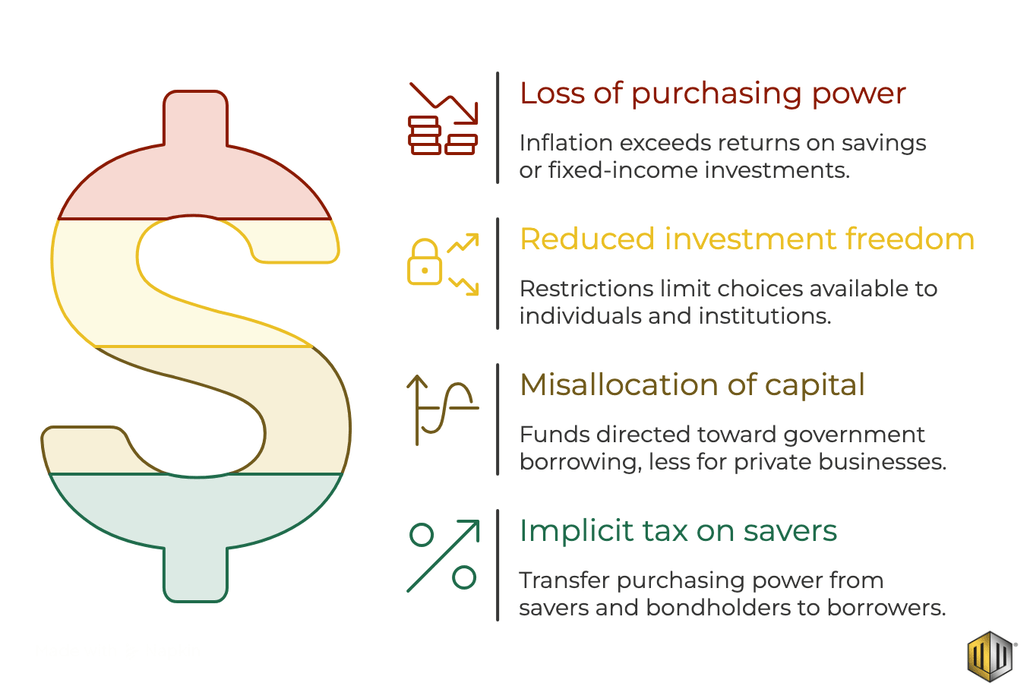
- Loss of purchasing power: When inflation exceeds the returns earned on savings or fixed-income investments, investors lose purchasing power even as their nominal balances increase.
- Reduced investment freedom: Capital controls, interest rate restrictions, and mandatory investment requirements can limit the choices available to individuals and institutions.
- Misallocation of capital: When regulations direct funds toward government borrowing, less capital may be available for private businesses and other productive activities.
- An implicit tax on savers: Reinhart and Sbrancia describe financial repression as a form of taxation because it can transfer purchasing power from savers and bondholders to borrowers without an explicit tax increase[1].
What assets perform well during financial repression?
Assets respond differently to financial repression depending on interest rates, inflation, and the restrictions imposed on financial markets.
Cash and fixed-rate bonds can be particularly vulnerable when inflation persistently exceeds their nominal returns. Other assets may offer some protection, although their performance isn’t guaranteed.
- Inflation-linked bonds adjust their principal according to changes in the Consumer Price Index, with interest payments calculated on the adjusted principal. This helps protect their purchasing power against inflation when held to maturity[7].
- Equities represent ownership in businesses, some of which can raise prices to offset inflation. Their ability to maintain profitability depends partly on how effectively they manage rising costs[8].
- Real estate may provide some protection against inflation through rising rental income and property values. Its effectiveness as an inflation hedge varies by property type, investment structure, and time horizon[9].
- Gold has historically served as a store of wealth independent of government-issued currency. Unlike government bonds and bank deposits, physical gold is nobody else’s liability, but government restrictions can also limit its usefulness in a financially repressed economy[10].
Could productive gold offer freedom from financial repression?
Physical gold provides an alternative to holding wealth entirely in government-issued currency and debt instruments. Unfortunately, storing it can incur costs and doesn’t generate income.
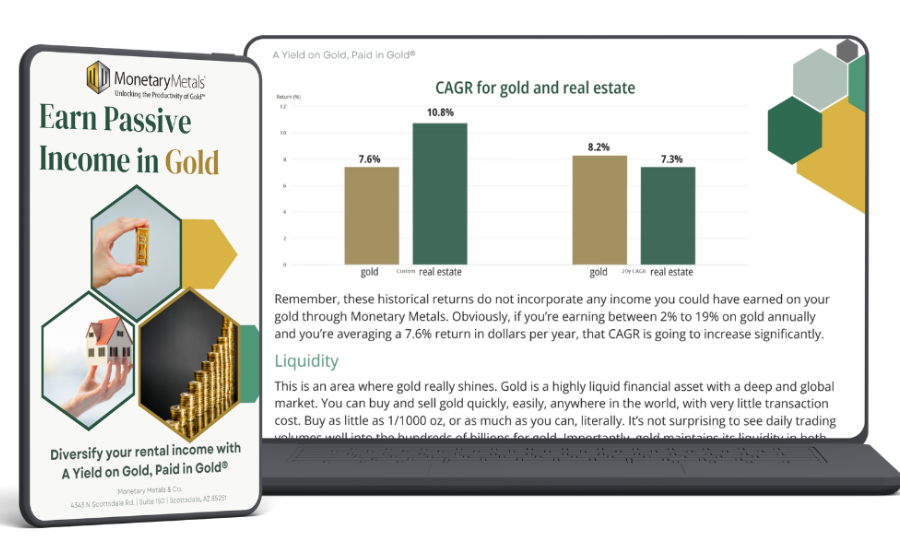
Qualified gold owners can earn passive income paid in additional ounces of gold. Doing so may offer freedom from financial repression by empowering them to reduce their reliance on interest payments denominated in government-issued currency.
Sources:
- https://www.imf.org/en/publications/wp/issues/2016/12/31/the-liquidation-of-government-debt-42610
- https://www.federalreservehistory.org/essays/regulation-q
- https://www.imf.org/external/pubs/ft/op/op190/pdf/part2.pdf
- https://ies.gov.in/arthapedia/concept/policy-rate
- https://www.rbi.org.in/upload/content/pdfs/66391.pdf
- https://www.federalreservehistory.org/essays/riegle-neal-act-of-1994
- https://www.treasurydirect.gov/marketable-securities/tips/
- https://www.schwab.com/learn/story/what-is-inflation
- https://www.elibrary.imf.org/view/journals/001/2009/090/article-A001-en.xml
- https://www.gold.org/goldhub/research/golds-long-term-expected-returns/money-no-more